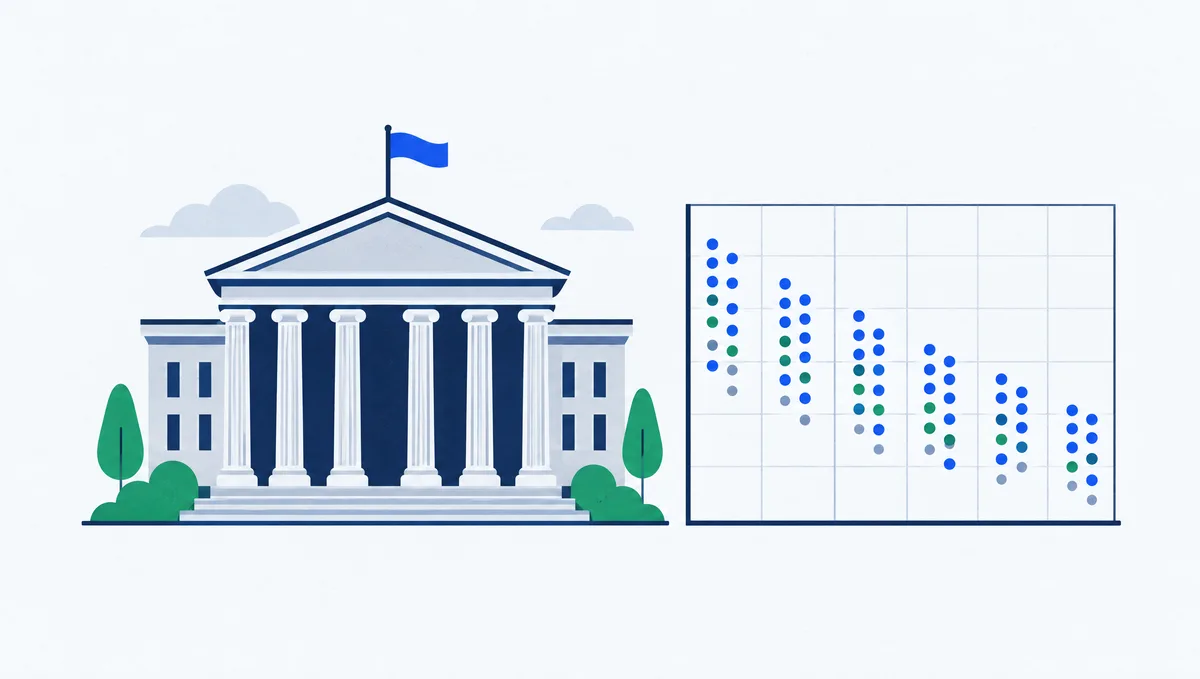
Four times a year, the Federal Reserve releases a chart that looks like a scatter of dots on a grid. Investors study it closely because it shows where Fed officials think interest rates are heading.
Where the dot plot comes from
At the March, June, September, and December meetings, the Fed publishes its Summary of Economic Projections (SEP). Each participant in the Federal Open Market Committee, both the Board governors and all twelve Reserve Bank presidents whether or not they vote that year, submits projections for economic growth, unemployment, inflation, and the federal funds rate. The rate projections are displayed as the dot plot.
How to read the chart
- Horizontal axis: the current year, the next two or three years, and the “longer run.”
- Vertical axis: the level of the federal funds rate.
- Each dot: one official’s view of the appropriate midpoint of the target range at the end of that year. Dots are anonymous.
The median dot for each year is the number most headlines report. If the current rate is higher than the median dot for year-end, officials are signaling cuts; if lower, hikes.
The longer-run dot
The longer-run dots show where officials think rates will settle once the economy is at full employment with 2% inflation, with no shocks. This is an estimate of the “neutral” rate, which neither stimulates nor restrains the economy. A rise in the longer-run median suggests officials think rates will need to stay structurally higher than before.
Reading more than the median
Dispersion
A tight cluster of dots suggests broad agreement. A wide spread signals uncertainty or disagreement, which can mean policy is more likely to change as data arrives.
Changes from the last release
The most market-moving information is often how the dots moved since the previous SEP. If the median for next year shifts up, markets may price in fewer rate cuts, pushing up Treasury yields and weighing on stocks.
The other projections
The SEP also includes median forecasts for GDP growth, the unemployment rate, and PCE inflation. Reading them alongside the dots tells you the story officials are telling themselves: for example, rate cuts because inflation is expected to fall, or because unemployment is expected to rise.
Why the dots are not a promise
Fed officials repeatedly stress that the dots are individual projections, not a plan or commitment. They depend on each official’s forecast of the economy, and forecasts change. Rate paths have often ended up far from where the dots pointed a year earlier. It is also worth remembering that not every dot belongs to a voter.
Dots vs. market pricing
Traders’ own expectations for rates, reflected in futures markets, often differ from the dots. When markets price in more cuts than the Fed projects, one side eventually has to adjust. Watching that gap is a useful way to judge where surprises may come from. For more on the committee itself, see how the Fed sets interest rates.